
Absa PMI rises above the neutral 50 mark, but employment subindex reverses gains


Financial services firm Absa's Purchasing Managers’ Index (PMI) rose by 4.9 points to 50.7 index points in September, returning to above the neutral 50-point mark after three consecutive months in contractionary territory.
The new sales orders index rebounded sharply and moved back above the neutral mark, while business activity recovered most of August’s steep decline.
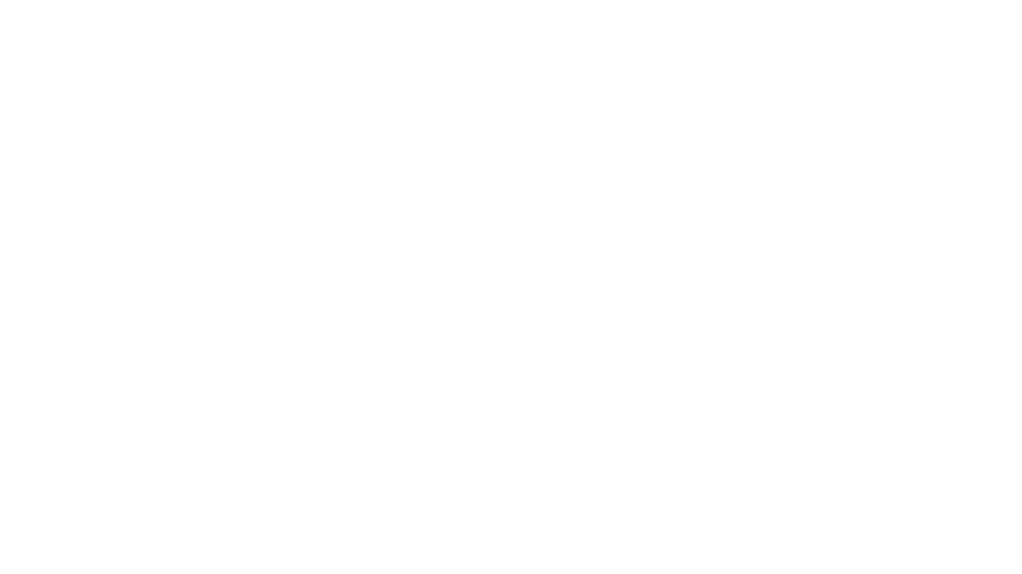
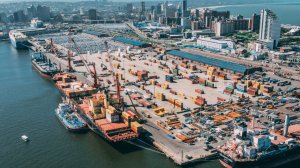
However, shipping delays at Durban harbour stand out as a significant bottleneck and likely kept the supplier deliveries index unusually elevated. The current high reading should not be interpreted as evidence that suppliers are struggling to keep pace with stronger demand, but rather as evidence of delivery delays, Absa says.
Respondents repeatedly flagged longer shipping times, delays in clearing containers and sharply higher freight costs.
Further, the employment index almost fully reversed August’s improvement, declining to 43.1 index points in September from 46.2 in August, which was up from 42.2 in July. This suggests that the improvement in new orders and activity has not yet been strong or sustained enough to alter manufacturers’ cautious approach to hiring, the bank says.
Price pressures also accelerated again in September and the purchasing price index reversed its recent downward trend, with respondents pointing to higher fuel, transport, logistics and other input costs.
The sharp increase in domestic fuel prices at the start of September added to the pressure, adds Absa.
The expected business conditions in six months’ time index edged up by 0.6 points to 55.3. While still below its long-term average, the reading suggests that purchasing managers remain cautiously positive about business conditions over the next six months.
While the September PMI is an improvement after a weak winter period, particularly given the sharp rebound in new orders, the signal is not uniformly positive as actual business activity remained just below the neutral mark, employment weakened, and order backlogs stayed subdued, Absa says.
Additionally, logistics disruptions appear to have artificially boosted the supplier deliveries component of the headline PMI, while purchasing price pressure accelerated again.
A sustained move above 50 over the coming months would provide more evidence that the manufacturing sector is entering a recovery, Absa says.
Meanwhile, the business activity index rebounded sharply to 49.3 in September from 40.2 in August, moving slightly above its July level.
While official August manufacturing production data is outstanding, July was a strong month for manufacturing output.
The new sales orders index improved by 10.5 index points to 50.8.
While export sales remained below the neutral 50-point mark, the export index rebounded to its best level since early 2025. This suggests that the improvement in new orders was not solely domestic.
However, the broader demand picture warrants caution. Respondent comments also point to a mixed environment, with some firms preparing for stronger seasonal demand while others report weaker customer commitments and few major projects on the horizon, Absa points out.
Margins also remain under pressure amid intense competition from imports and higher input costs.
Meanwhile, the supplier deliveries index remained broadly unchanged at 58.4, after 58.6 in August. A reading above 50 indicates that supplier delivery times lengthened relative to the previous month.
In September, respondent comments suggest that logistics disruptions were an important driver. Several respondents specifically highlighted delays at Durban harbour, longer shipping schedules and substantially higher freight and transport costs.
The elevated September supplier deliveries index reading should not be interpreted as an unambiguously positive demand signal, says Absa.
Further, the inventories index jumped to 52.2 in September from 43.6, moving back above the neutral 50-point mark. Together with a rise in purchase commitments, this may suggest that some manufacturers are rebuilding stocks following weakness in recent months or preparing for stronger seasonal demand.
However, with order backlogs still subdued, it is too early to interpret the inventory build as evidence of a broad demand upswing.
The purchasing price index reversed its recent downward trend, rising by 3.9 points to 71.1 in September. This remains almost 15 points below the May peak but indicates a renewed acceleration in cost pressures relative to August. Respondent comments highlight transport, logistics and other input costs as important contributors.
The sharp increase in domestic fuel prices at the start of September added directly to these pressures. Firms also mentioned higher supplier delivery charges, increases in paper prices, shortages of some plastic inputs and continued pressure on margins, the bank says.
Article Enquiry
Email Article
Save Article
Feedback
To advertise email advertising@creamermedia.co.za or click here
Projects
Latest News
Showroom
Axiom Hydraulics is a trusted leader in South Africa’s hydraulic industry, delivering world-class components, systems, and engineering expertise...
VISIT SHOWROOM
Supplier & Distributor of the Widest Range of Accurate & Easy-to-Use Alcohol Breathalysers
VISIT SHOWROOM
Press Office
Announcements
What's On
Subscribe to improve your user experience...
Option 1 (equivalent of R125 a month):
Receive a weekly copy of Creamer Media's Engineering News & Mining Weekly magazine
(print copy for those in South Africa and e-magazine for those outside of South Africa)
Receive daily email newsletters
Access to full search results
Access archive of magazine back copies
Access to Projects in Progress
Access to ONE Research Report of your choice in PDF format
Option 2 (equivalent of R375 a month):
All benefits from Option 1
PLUS
Access to Creamer Media's Research Channel Africa for ALL Research Reports, in PDF format, on various industrial and mining sectors
including Electricity; Water; Energy Transition; Hydrogen; Roads, Rail and Ports; Coal; Gold; Platinum; Battery Metals; etc.
Already a subscriber?
Forgotten your password?
Receive weekly copy of Creamer Media's Engineering News & Mining Weekly magazine (print copy for those in South Africa and e-magazine for those outside of South Africa)
➕
Recieve daily email newsletters
➕
Access to full search results
➕
Access archive of magazine back copies
➕
Access to Projects in Progress
➕
Access to ONE Research Report of your choice in PDF format
RESEARCH CHANNEL AFRICA
R4500 (equivalent of R375 a month)
SUBSCRIBEAll benefits from Option 1
➕
Access to Creamer Media's Research Channel Africa for ALL Research Reports on various industrial and mining sectors, in PDF format, including on:
Electricity
➕
Water
➕
Energy Transition
➕
Hydrogen
➕
Roads, Rail and Ports
➕
Coal
➕
Gold
➕
Platinum
➕
Battery Metals
➕
etc.
Receive all benefits from Option 1 or Option 2 delivered to numerous people at your company
➕
Multiple User names and Passwords for simultaneous log-ins
➕
Intranet integration access to all in your organisation